ATM processing
ATM processing for cannabis dispensaries: check fit before you switch.
Processing is what connects your ATM to the customer’s bank and pays the money back to you. For a cannabis business, whether a processor will take you on comes first.
Final artwork and fit require approval.
We get our wraps from Get Branded.
Illustrative wrap concept.
What processing does
When a customer withdraws cash, the ATM sends the request to a processor. The processor routes it through a debit or ATM network to the customer’s card issuer, which approves or declines it. Later, the processor settles the dispensed cash and any surcharge owed to the machine’s owner into a designated account.
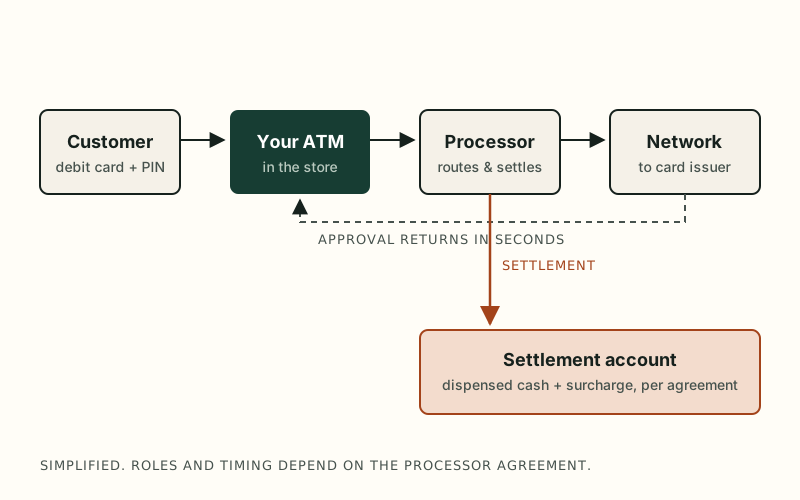
With placement, this is the provider’s relationship. If you own the ATM, the processing agreement is in your business’s name and its terms matter as much as the equipment.
Fit for cannabis merchants
Processors and their sponsor banks set their own policies on cannabis-related merchants, and those policies change. We review whether a processing option fits your license, state and ownership structure before you buy equipment or give notice on a current agreement. We cannot promise acceptance — be careful with anyone who does.
Questions that decide fit:
- Which license types and states the processor currently accepts.
- Whether the settlement account can be at your bank or credit union, and whether that institution accepts the deposits.
- Whether ownership changes, new locations or license renewals trigger a fresh review.
What a processor may ask for
Requirements differ by processor. Commonly requested items include:
- Legal business name, entity documents and tax ID
- Your state cannabis license and its status
- Owners and officers, with identification
- The location address and the ATM model and serial number
- Settlement account detailsProvide these directly to the processor through its own secure process — never through this website’s form.
Settlement and reporting
Ask how often funds settle, into which account, and whether dispensed cash and surcharge arrive together or separately. Ask what reports you get — transactions per day, average withdrawal, declines, downtime — because those numbers drive your replenishment plan. Some agreements also pay a per-transaction amount from the networks; ask whether yours does and who keeps it.
Switching processors
- Read the current contract: term, automatic renewal, notice period and early-termination fees.
- Confirm fit with the new processor first — before giving notice.
- Check the machine: model, software version, communications, and whether it needs new encryption keys or a configuration visit.
- Plan the cut-over for a quiet day, with cash in the machine and staff told what to expect.
- Compare the first settlement and reports against what you were told.
A note on banking
Banks and credit unions that serve cannabis businesses follow federal anti-money-laundering expectations, including FinCEN guidance issued specifically for marijuana-related businesses. That affects settlement accounts and cash deposits, so involve your financial institution early.
Source: FinCEN — FIN-2014-G001, BSA Expectations Regarding Marijuana-Related Businesses (Feb. 14, 2014) · retrieved 2026-10-20
This site covers ATMs that dispense physical cash from a customer’s own account. It does not cover “cashless ATM” or point-of-sale debit arrangements. For ATM processing in general (not cannabis-specific), see ATM processing at ATMMachines.com.
Next step
Review your ATM processing.
Bring your machine model, current processor and contract dates. We’ll check fit for your license and state before you change anything.